Medicare Advantage 2026: Enrollment & Insider Tips
Maximizing your Medicare Advantage in 2026 involves understanding critical enrollment deadlines and applying strategic insider tips for optimal coverage.
Navigating healthcare choices, especially for seniors, can feel overwhelming. However, understanding how to maximize your Medicare Advantage 2026 plan is crucial for securing the best possible coverage and benefits tailored to your needs. This guide will help you understand the critical enrollment periods and equip you with insider knowledge to make informed decisions.
Understanding Medicare Advantage: A 2026 Perspective
Medicare Advantage, also known as Medicare Part C, offers an alternative way to receive your Medicare benefits. Instead of Original Medicare (Parts A and B) directly, private insurance companies approved by Medicare provide these plans. These plans must cover all services that Original Medicare covers, but they often include additional benefits like vision, dental, hearing, and prescription drug coverage (Part D) in one comprehensive package. For 2026, these plans continue to evolve, offering new incentives and expanded networks, making it essential to review your options carefully.
Choosing a Medicare Advantage plan involves more than just selecting the lowest premium. It requires a detailed assessment of your health needs, preferred doctors, and financial situation. Many plans offer zero-dollar premiums, but this doesn’t mean they’re free. You’ll still pay your Medicare Part B premium, and plans may have deductibles, copayments, and coinsurance. The value lies in the comprehensive benefits and coordinated care often provided, which can lead to better health outcomes and predictable costs.
What’s new for 2026 in Medicare Advantage?
- Expanded telehealth services to improve access, particularly in rural areas.
- Increased focus on supplemental benefits addressing social determinants of health, such as healthy food, transportation, and in-home support.
- New plan designs that integrate chronic care management more effectively, providing personalized support for specific conditions.
The landscape of Medicare Advantage is dynamic, with annual adjustments to benefits, networks, and costs. Staying informed about these changes is key to ensuring your plan continues to meet your requirements. For 2026, expect a continued push towards value-based care and preventative services, reflecting a broader shift in healthcare policy to keep beneficiaries healthier and reduce overall costs.
In summary, Medicare Advantage plans for 2026 present a compelling option for many beneficiaries seeking integrated care and additional benefits. A thorough understanding of how these plans function and what they offer is the first step toward making an optimal choice. It’s not just about coverage, but about comprehensive well-being.
Key Enrollment Deadlines for Medicare Advantage in 2026
Missing an enrollment deadline for Medicare Advantage can have significant consequences, potentially leading to gaps in coverage or higher premiums. Understanding the critical dates for 2026 is paramount for anyone looking to enroll, switch, or drop a plan. These deadlines are strictly enforced by Medicare, so proactive planning is essential to ensure you secure the best possible coverage without interruption.
The main period for most people to make changes to their Medicare Advantage plan is during the Annual Enrollment Period (AEP). However, other specific windows exist depending on your circumstances. Being aware of these different enrollment periods allows you to act decisively when the time is right, preventing unnecessary stress and ensuring continuity of care. 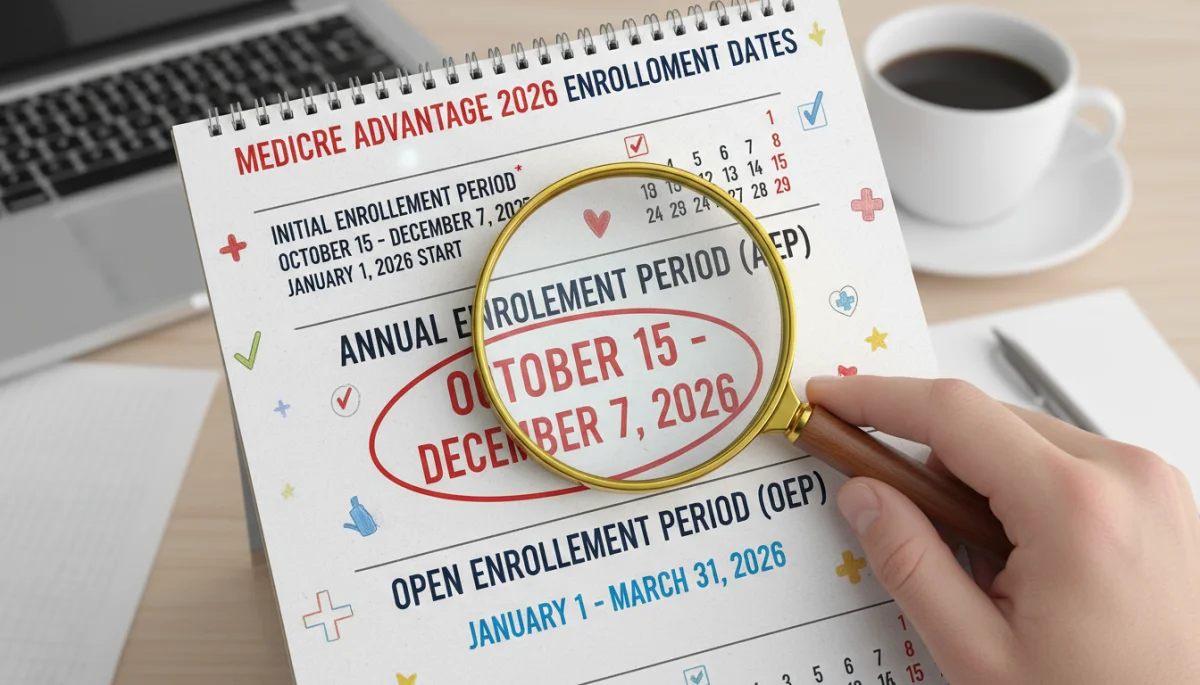

The Annual Enrollment Period (AEP): October 15 – December 7
This is the most crucial time for most beneficiaries. During the AEP, you can:
- Switch from Original Medicare to a Medicare Advantage plan.
- Switch from one Medicare Advantage plan to another.
- Switch from a Medicare Advantage plan back to Original Medicare.
- Join, switch, or drop a Medicare Part D prescription drug plan.
Any changes made during this period will take effect on January 1, 2026. This window provides an opportunity to reassess your current plan against new offerings, ensuring it still aligns with your health needs and financial situation. It’s a period designed for flexibility and optimization, allowing beneficiaries to adapt to new health circumstances or changes in plan benefits.
Other important enrollment periods
Beyond the AEP, there are Special Enrollment Periods (SEPs) that allow you to make changes outside of the standard windows. These are triggered by specific life events, such as moving to a new area, losing other coverage, or qualifying for Extra Help with prescription drug costs. Understanding when you might qualify for an SEP is vital, as these periods provide a safety net for unexpected changes in your life. Additionally, the Medicare Advantage Open Enrollment Period (MA OEP), from January 1 to March 31, allows individuals already enrolled in a Medicare Advantage plan to switch to a different Medicare Advantage plan or return to Original Medicare and join a Part D plan. This period is specifically for those already in an MA plan and provides an additional opportunity for adjustment early in the year.
In conclusion, meticulously tracking Medicare Advantage enrollment deadlines for 2026 is a critical step in maintaining optimal coverage. Whether it’s the widely known AEP or a lesser-known SEP, being informed about these timelines empowers you to make timely and effective decisions regarding your healthcare benefits.
Insider Tip 1: Analyze Your Healthcare Needs Thoroughly
One of the most common pitfalls in choosing a Medicare Advantage plan is failing to conduct a comprehensive assessment of your personal healthcare needs. Many beneficiaries simply renew their existing plan or choose one based on a recommendation without truly understanding if it still serves them best. For 2026, a deeper dive into your health history, anticipated medical services, and prescription requirements is more critical than ever, given the evolving nature of healthcare and plan offerings.
Start by reviewing your medical records from the past year. What doctors did you see? What specialists did you consult? What medications were prescribed, and how frequently? This retrospective analysis provides a baseline for predicting your future needs. Consider any new diagnoses, chronic conditions, or upcoming procedures that might influence your choice. For instance, if you anticipate needing physical therapy or specialized care, confirm that potential plans cover these services adequately and that your preferred providers are in-network.
Beyond the basics: what to consider
- Prescription drug coverage: Check the plan’s formulary to ensure all your current medications are covered, ideally at a reasonable cost. Pay attention to tier levels and any restrictions.
- Doctor and hospital networks: Verify that your primary care physician and any specialists you see are part of the plan’s network. Out-of-network care can be significantly more expensive.
- Supplemental benefits: Evaluate additional benefits like dental, vision, hearing, gym memberships, and transportation. These can add substantial value and reduce out-of-pocket expenses.
Don’t just look at the premiums. A plan with a low premium might have higher deductibles, copayments, or a higher out-of-pocket maximum. Conversely, a higher premium might offer more comprehensive coverage and lower costs for services you frequently use. It’s a balance between upfront costs and potential future expenses. Use online comparison tools and speak with licensed insurance agents who can help you weigh these factors against your specific needs.
Ultimately, a thorough analysis of your individual healthcare needs for 2026 is the cornerstone of maximizing your Medicare Advantage benefits. This proactive approach ensures you select a plan that not only covers your current requirements but also anticipates future health considerations, providing peace of mind and financial security.
Insider Tip 2: Leverage Plan Comparison Tools and Resources
In today’s digital age, a wealth of information is available at your fingertips, yet many Medicare beneficiaries still rely on outdated methods or limited information when choosing a plan. Leveraging official and reputable plan comparison tools and resources is an essential insider tip for maximizing your Medicare Advantage in 2026. These tools provide an objective, comprehensive view of available plans, allowing for informed decision-making based on your specific criteria.
The official Medicare.gov Plan Finder is arguably the most powerful tool at your disposal. It allows you to enter your ZIP code, current medications, and preferred pharmacies to compare plans side-by-side. This platform provides detailed information on premiums, deductibles, copayments, and out-of-pocket maximums for each plan. Crucially, it also shows which plans cover your specific prescription drugs and at what cost, a feature that can save hundreds or even thousands of dollars annually.
Beyond the official tools: other valuable resources
- State Health Insurance Assistance Programs (SHIPs): These programs offer free, unbiased counseling and assistance with Medicare questions. Counselors can help you understand your options and compare plans.
- Licensed independent agents: While they earn commissions, independent agents can represent multiple insurance companies, offering a broader range of plans than captive agents who work for a single company. Ensure they are licensed and reputable.
- Online comparison websites: Many reputable third-party websites offer comparison tools. Always cross-reference information with Medicare.gov to ensure accuracy and up-to-date details.
When using these resources, pay close attention to the details. Don’t just glance at the summary. Dive into the plan’s Evidence of Coverage (EOC) document, which provides a comprehensive breakdown of all benefits, limitations, and exclusions. Look for details on prior authorization requirements for services or medications, and understand the appeals process if a claim is denied. Understanding these nuances can prevent unexpected costs and frustrations down the line.
In conclusion, effectively utilizing the diverse range of plan comparison tools and resources available is an invaluable insider tip for navigating the Medicare Advantage landscape in 2026. These platforms empower you to cut through the complexity, ensuring you select a plan that is not only cost-effective but also perfectly aligned with your health and financial objectives.
Insider Tip 3: Scrutinize Network Restrictions and Referrals
A frequently overlooked aspect of Medicare Advantage plans is the structure of their provider networks and referral requirements. Many beneficiaries assume their current doctors will be covered, only to find out too late that their preferred physicians or specialists are out-of-network. For 2026, understanding and scrutinizing these network restrictions and referral protocols is a critical insider tip to avoid unexpected costs and ensure continuity of care.
Most Medicare Advantage plans operate with either Health Maintenance Organization (HMO) or Preferred Provider Organization (PPO) models. HMO plans typically require you to choose a primary care physician (PCP) within the plan’s network, and you’ll need a referral from your PCP to see specialists. PPO plans offer more flexibility, allowing you to see out-of-network providers, though usually at a higher cost. For 2026, it’s essential to confirm not only that your current doctors are in-network but also that your preferred hospitals and ancillary service providers (e.g., labs, imaging centers) are included.
Key questions to ask about networks and referrals
- Is my primary care physician (PCP) in the plan’s network?
- Are my specialists (cardiologist, endocrinologist, etc.) in-network?
- What hospitals and emergency facilities are covered by the plan?
- Does the plan require referrals for specialist visits, and what is the process?
- What are the out-of-pocket costs for out-of-network care, if applicable?
Don’t rely solely on the plan’s general network directory, as these can sometimes be outdated. It’s best practice to directly contact your doctors’ offices and the insurance plan to confirm their participation for 2026. This dual verification helps prevent any surprises once your coverage begins. Also, consider if you travel frequently; some plans, especially HMOs, offer very limited or no coverage outside their service area, which could be problematic if you spend extended periods away from home.
In essence, a meticulous review of network restrictions and referral processes is an indispensable insider tip for anyone aiming to maximize their Medicare Advantage experience in 2026. This due diligence ensures that your chosen plan aligns with your existing healthcare relationships and lifestyle, safeguarding both your health and your finances.
Insider Tip 4: Understand Out-of-Pocket Maximums and Cost-Sharing
While premiums often grab the most attention, understanding a Medicare Advantage plan’s out-of-pocket maximum (OOPM) and various cost-sharing mechanisms is a crucial insider tip for truly maximizing your benefits in 2026. The OOPM is the most you’ll have to pay for covered services in a calendar year, after which the plan pays 100% of the costs. This cap provides a vital layer of financial protection, especially for those with significant health needs.
Cost-sharing includes deductibles, copayments, and coinsurance. A deductible is the amount you must pay out of pocket before your plan starts to pay. Copayments are fixed amounts you pay for specific services, like a doctor’s visit or a prescription. Coinsurance is a percentage of the cost of a service you pay after you’ve met your deductible. For 2026, these figures can vary widely between plans, and a seemingly low premium plan might have higher cost-sharing, potentially leading to greater overall expenses if you frequently use medical services.
Evaluating cost-sharing for different scenarios
- High-utilization scenario: If you anticipate frequent doctor visits, specialist consultations, or hospital stays, a plan with lower copayments and coinsurance, even if it has a slightly higher premium, might be more cost-effective.
- Low-utilization scenario: For those who rarely visit the doctor, a plan with a lower premium and higher deductible might be suitable, provided the OOPM is still manageable.
- Prescription drug costs: Beyond the Part D deductible, evaluate the copayments or coinsurance for your specific medications across different tiers. Generic drugs often have lower costs than brand-name or specialty drugs.
It’s important to differentiate between the OOPM for medical services and the separate out-of-pocket costs for prescription drugs. While Medicare Advantage plans often bundle Part D, the drug costs may not count towards the medical OOPM. Always clarify this distinction. Furthermore, some plans offer additional benefits that don’t count towards the OOPM, such as over-the-counter allowances or gym memberships, which can still add significant value.
In conclusion, a deep understanding of out-of-pocket maximums and the intricacies of cost-sharing is an indispensable insider tip for selecting a Medicare Advantage plan in 2026. By carefully comparing these financial aspects, you can protect yourself from unforeseen medical expenses and ensure your chosen plan offers true financial security alongside quality healthcare.
Insider Tip 5: Review Plan Star Ratings and Member Satisfaction
While the tangible benefits and costs are crucial, an often-overlooked insider tip for maximizing your Medicare Advantage in 2026 is to scrutinize a plan’s Star Rating and overall member satisfaction. These qualitative measures provide valuable insights into the quality of care, customer service, and overall experience offered by a plan. A high Star Rating indicates that a plan performs exceptionally well in several key areas, reflecting a positive experience for its members.
Medicare uses a 5-star rating system to help beneficiaries compare the quality and performance of Medicare Advantage and Part D plans. These ratings are updated annually and cover various aspects, including how well plans help members stay healthy, manage chronic conditions, provide customer service, and ensure member satisfaction. A 5-star rating is the highest possible, indicating excellent performance. Plans with lower ratings might signal areas where the plan falls short, potentially leading to frustrations or subpar care.
What do Medicare Star Ratings evaluate?
- Quality of care: How well the plan prevents illness and manages chronic conditions.
- Member experience: Surveys on how members feel about the plan and their doctors.
- Customer service: How well the plan handles appeals, grievances, and provides information.
- Plan performance: Overall efficiency and effectiveness of the plan’s operations.
Beyond the Star Ratings, seek out independent reviews and testimonials from current members. While individual experiences can vary, a pattern of positive or negative feedback can be very telling. Websites, forums, and consumer advocacy groups often provide platforms for members to share their experiences. Pay attention to comments regarding ease of access to care, responsiveness of customer service, and how claims are handled. These real-world insights can complement the official ratings and give you a more complete picture of what to expect.
In summary, incorporating a review of Medicare Star Ratings and member satisfaction into your decision-making process is a smart insider tip for selecting a Medicare Advantage plan in 2026. These indicators of quality and service can significantly impact your overall healthcare experience, ensuring you choose a plan that not only covers your needs but also delivers on its promise of quality and support.
| Key Point | Brief Description |
|---|---|
| Enrollment Deadlines | Crucial dates like AEP (Oct 15 – Dec 7) impact coverage for 2026. |
| Healthcare Needs Analysis | Thoroughly review doctors, medications, and anticipated services. |
| Network Restrictions | Verify doctors and hospitals are in-network to avoid higher costs. |
| Star Ratings & Satisfaction | Assess plan quality and member experience for informed choices. |
Frequently Asked Questions About Medicare Advantage 2026
The primary period is the Annual Enrollment Period (AEP), running from October 15 to December 7 each year. During this time, you can enroll in a new plan, switch plans, or return to Original Medicare, with changes effective January 1, 2026.
Yes, you might qualify for a Special Enrollment Period (SEP) due to specific life events like moving, losing other coverage, or qualifying for Extra Help. Additionally, the Medicare Advantage Open Enrollment Period (Jan 1 – Mar 31) allows current MA plan members to switch plans or return to Original Medicare.
Medicare Star Ratings are a 1-to-5 scale assessing a plan’s quality and performance. They help beneficiaries compare plans based on care quality, member experience, and customer service. A higher rating generally indicates a better overall plan experience.
Most Medicare Advantage plans (MA-PDs) include prescription drug coverage (Part D). It’s crucial to check the plan’s formulary to ensure all your current medications are covered and to understand the associated costs, such as deductibles, copayments, and coinsurance.
You should always contact your doctors’ offices directly and the Medicare Advantage plan provider to confirm their participation for 2026. This dual verification ensures your preferred healthcare providers are in-network, helping you avoid unexpected out-of-pocket costs.
Conclusion
Maximizing Your Medicare Advantage in 2026 is not merely about selecting a plan; it’s about strategic engagement with your healthcare choices. By diligently adhering to key enrollment deadlines, thoroughly analyzing your personal health needs, leveraging comprehensive comparison tools, scrutinizing network details, and understanding cost-sharing mechanisms, you empower yourself to make the most informed decision. Furthermore, considering plan Star Ratings and member satisfaction provides a holistic view of a plan’s quality. Embracing these insider tips will ensure you secure better coverage that truly aligns with your well-being and financial security in the coming year.